When our client first came to us, she was just 21 years old. She was living at home with her parents and had a good job in HR on a solid income. Because her living costs were low, she was able to save a large share of what she earned. The question was what to do with those savings.
She could have kept building up cash until she was ready to buy a home of her own. Instead, she decided to put her money to work.
She didn't wait until she was ready to buy her own home before entering the property market. She used the position she had at 21 to start building assets.
And because she started so young, she had something valuable on her side: time.
Two Investments in Just Over a Year
This wasn't about finding a home she wanted to live in. Both purchases were investment decisions, chosen for markets and properties with the fundamentals to support capital growth and a strong rental return.
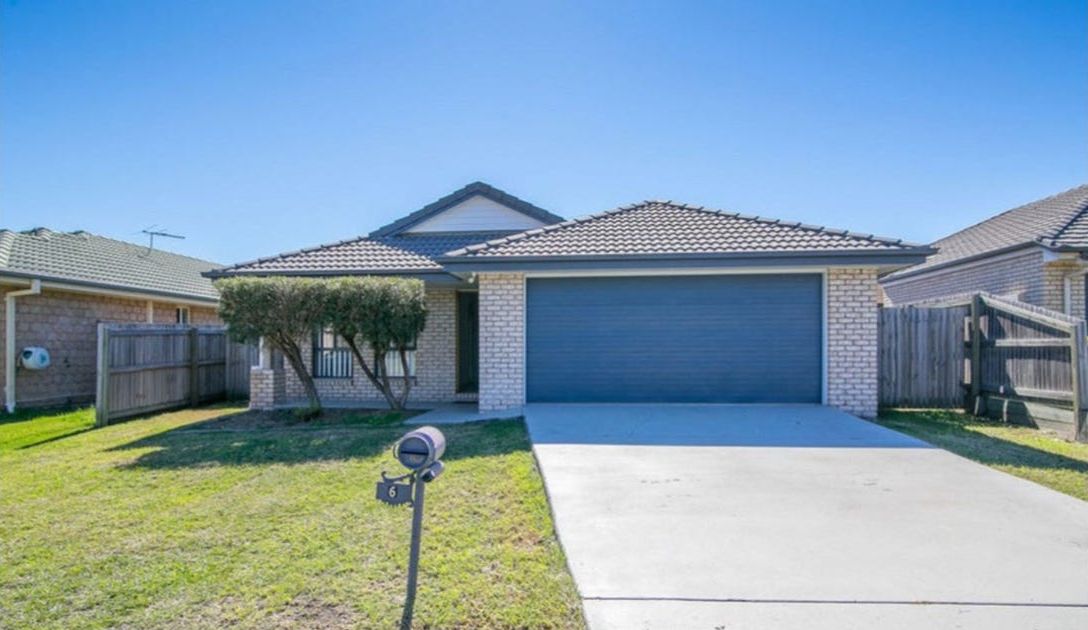
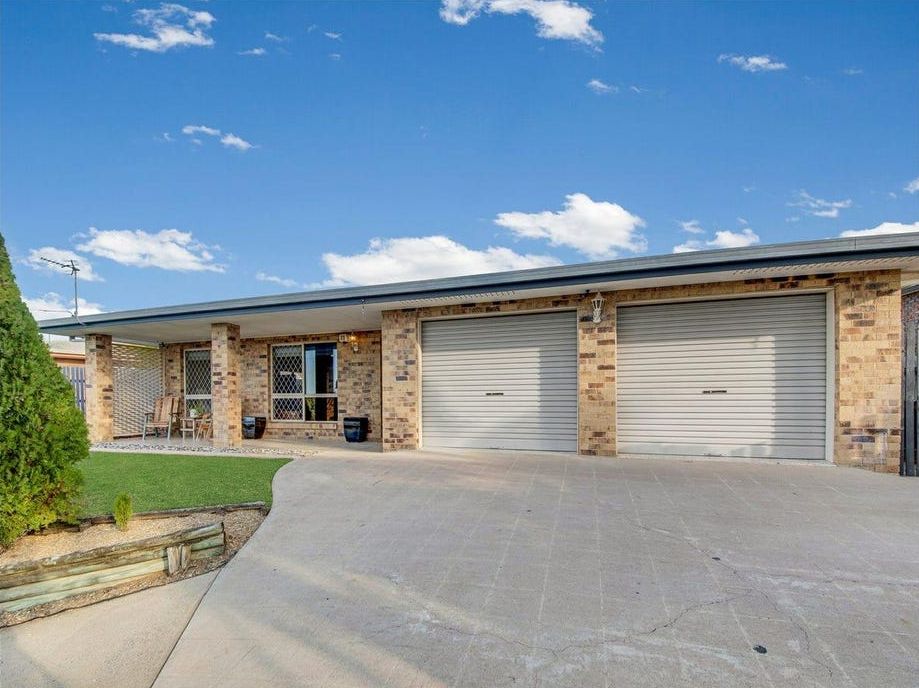
Both properties are earning more than they cost to hold. They are positively geared, so the rent is covering the cost of the properties and, based on her circumstances, producing positive cash flow.
What Two Purchases Have Built
Together, our client has bought $868,000 of property, beginning at 21. Those properties are now worth approximately $1.495 million, an increase of $627,000, and they are bringing in approximately $63,180 a year in gross rent.
What Happens Next Is Up to Her
What we like about this story is that we don't yet know how it ends. That's the point.
She may hold both properties for decades. She may keep building a portfolio. She may sell one. Or she may use the equity she has built to help her buy the home she ultimately wants to live in.
Her savings became the foundation for her first investment. The growth in those investments then strengthened her overall financial position, and all of it happened at an age when many people haven't started thinking about property.
The greatest thing her portfolio has created isn't just equity. It's options.
The Advantage of Starting Young
There is no single age at which someone should invest, and property won't suit everyone. But this story shows the potential advantage of starting early when your circumstances allow it.
When you're young, earning well and living at home, it's easy to assume you have plenty of time to make these decisions later. You do. But time can also be one of your greatest advantages.
She made her savings work for her. At 21 she bought her first investment property. A little over a year later she bought her second. Today they have grown by approximately $627,000 combined, while earning gross yields of 7.1% and 7.5% on their purchase prices.
Whatever she decides to do next, she has already created something valuable: choice. The choice to keep investing, to use her equity toward her own home, or to hold for the long term, with a significant head start because she put her money to work early.
*Figures are for two properties bought through Property Home Base's Strategic Investment service, in Raceview (April 2022, $482,000) and Telina (July 2023, $386,000), at estimated current values of $850,000 and $645,000. Average annual growth is total growth divided by the years held. Gross rental yield is the current weekly rent over a year, divided by the original purchase price, and is not a net return. Estimated values are not formal valuations. Past performance is not a guarantee of future property values, rental returns or investment performance. Individual results vary. This is general information and not financial advice.